Geopolitical risk and the UK inflation outlook
Recent developments in the Middle East, as reported by international media, have refocused market attention on a perennial risk: the impact of geopolitical instability on global oil prices. While not a UK-specific event, the potential for sustained conflict in a key oil-producing region represents a significant external shock to the British economy. For UK markets, the primary transmission mechanism is clear: any material and sustained rise in the Brent crude price directly feeds into domestic inflation, complicating the Bank of England’s task and influencing fiscal policy.
This development is being watched closely now because the UK economy remains in a delicate phase of disinflation. The Consumer Prices Index (CPI) has fallen significantly from its peak, but the Bank of England’s Monetary Policy Committee (MPC) has repeatedly cited persistent services inflation and wage growth as reasons for caution. A new supply-side shock from energy markets could stall or even reverse recent progress, affecting every UK household and business through higher transport, heating, and manufacturing costs. The trigger is geopolitical, but the implications are squarely macroeconomic for the UK.
The oil price channel to UK inflation
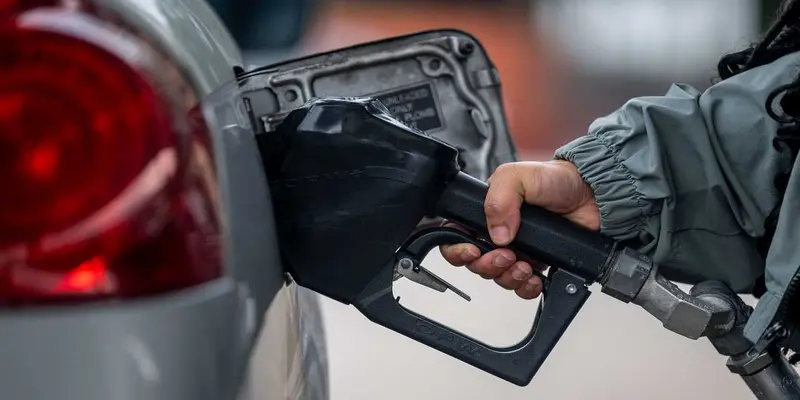
The immediate market signal from rising tensions is a risk premium being priced into oil futures. For the UK, which is a net importer of crude oil, this translates into higher input costs across the economy. The Office for National Statistics (ONS) includes fuel and energy costs directly in its basket of goods for calculating CPI. Historically, sharp spikes in the oil price, such as those seen following Russia’s invasion of Ukraine, have led to immediate and pronounced upward pressure on the headline inflation rate.
This matters beyond the petrol pump. Energy is a fundamental cost for industry, logistics, and agriculture. Higher Brent crude prices can therefore filter through to core inflation measures over time, affecting the price of goods and services that are not directly energy-related. The Bank of England’s models will be stress-tested against various oil price scenarios, with MPC members likely to voice heightened concern over the inflation outlook if volatility persists.
Implications for monetary and fiscal policy
For the Bank of England, a commodity-driven inflationary pulse presents a familiar dilemma. Such shocks are typically viewed as temporary, but their effect on household inflation expectations can become entrenched. The MPC’s recent communications have emphasised data dependency, and a renewed climb in headline CPI caused by energy would likely reinforce a cautious stance on interest rate cuts. Markets may consequently recalibrate their expectations for the timing and pace of monetary easing in 2024.
On the fiscal side, HM Treasury faces a dual challenge. Firstly, higher inflation would increase the cost of servicing index-linked gilts. Secondly, it could trigger higher future payments for state pensions and benefits, which are uprated by inflation metrics. While the current government’s fiscal rules are based on a five-year forecast horizon, a sustained oil price shock could necessitate a reassessment of spending priorities or tax policies to maintain market credibility, especially with the Office for Budget Responsibility (OBR) monitoring debt sustainability closely.
Market and sectoral exposures in the UK
The impact across UK markets and sectors would be uneven. The FTSE 100, with its heavy weighting in energy majors like BP and Shell, could see support from higher oil prices, potentially outperforming the more domestically focused FTSE 250 in the short term. Conversely, sectors with high energy intensity or consumer-facing businesses, such as transportation, manufacturing, and retail, could face margin compression and weaker demand.
For UK investors and pension funds, the situation underscores the importance of geopolitical risk as a non-diversifiable market factor. It may also renew scrutiny on the UK’s long-term energy security strategy and its transition plans, with debates around domestic North Sea production and renewable investment likely gaining prominence in political and financial discourse.
In conclusion, while the immediate event is external, its potential to disrupt the UK’s fragile disinflationary path is substantial. The key signal for UK markets is not the conflict itself, but the durability of any oil price spike it causes. Investors and policymakers will be monitoring forward curves for Brent crude and inflation swap rates closely, as these will provide clearer indicators of whether this geopolitical risk is translating into a sustained economic headwind. The coming weeks will test the resilience of recent economic forecasts and the preparedness of UK institutions for another external supply shock.
Other Articles That May Interest You
- Crypto Infrastructure Investment Signals Institutional Market Maturation
- Consumer Confidence Falls: What It Means for Your UK Finances
Source:
https://www.wcvb.com/article/how-the-iran-conflict-could-affet-your-wallet/70594293